The Tax Code Was Written for Real Estate Investors: 4 Pillars of Real Estate Tax Benefits

One of my partners netted over a million dollars last year and paid effectively zero in taxes. Now, I have never quite gotten to that point myself, but I have saved a significant amount of money on my active income over the years by simply investing in commercial real estate. And the reason that is possible has nothing to do with loopholes, shady accounting, or offshore bank accounts. It is because the tax code was literally written to reward real estate investors.

Today, I am going to walk you through exactly how he did it and, more importantly, how you can start using the same strategies in your own portfolio. But first, a disclaimer: I am not a CPA. This is educational content, not tax advice. Work with a CPA who specializes in real estate strategy. Got it? Good. Let's dive in.

Quick context before we dig in: every strategy below assumes you already own commercial real estate. If you're still working through how to buy your first commercial property, focus there first — these tax benefits unlock once you have an asset in your name.

The W-2 Approach to Real Estate Taxes (And Why It Is Costing You)

Most real estate investors handle their taxes in a pretty simple way. They buy a building, collect rent, pay taxes on the income. They treat it like a landlord filing a Schedule E: deduct your expenses, pay what is left. Maybe they depreciate the building on a straight-line schedule over 27.5 years for residential or 39 years for commercial. If the building is worth a million dollars, that is about $25,000 a year in depreciation. Decent, but nothing that is going to change your life.

Maybe at some point they do a 1031 exchange to defer gains on a sale. And that is about it. Buy, collect, depreciate slowly, maybe 1031 somewhere along the way, and eventually pay capital gains and depreciation recapture when it is all said and done.

I call this the W-2 approach. It is not wrong. But it is incomplete. And the investors paying almost nothing in taxes, the ones operating on a completely different framework, they are using the full toolkit that the tax code provides.

"The W-2 approach to real estate taxes is not wrong. It is just incomplete. The investors paying almost nothing operate on a completely different framework."

Why the Tax Code Was Written for Real Estate Investors

This is not some conspiracy theory or hidden secret. The tax code treats real estate differently on purpose. It goes all the way back to the 1986 Tax Reform Act, which codified structural advantages for real estate investors. Congress wanted to incentivize real estate development because it generates massive benefits for communities.

Think about it. If you build a 250-unit apartment complex, that is 250 people who can now move into the area. They are spending money locally, paying income tax, working jobs. The local government benefits enormously from the property tax base you just created. So Congress essentially made a deal: you take on the risk of building, improving, and maintaining real estate, and we will give you significant tax advantages in return.

The real estate tax benefits are not loopholes. They are features. And the four pillars that sophisticated investors use to minimize their tax burden are depreciation, cost segregation, 1031 exchanges, and borrowing against equity instead of selling.

The 4 Pillars of Real Estate Tax Benefits

01
Depreciation
02
Cost Segregation
03
1031 Exchanges
04
Borrow, Don't Sell

Pillar 1: Depreciation in Real Estate

Here is the baseline that every investor should understand. The IRS lets you depreciate real estate over time, essentially writing off the cost of the building (not the land) as a paper expense against your income. For residential properties, that schedule is 27.5 years. For commercial, it is 39 years.

So let me give you a real example. Say you buy a commercial building for $1 million, and the building (minus land) is worth about $800,000. Over 39 years, you get to deduct roughly $20,500 per year in depreciation. You did not actually spend that money. It is a paper loss. But it reduces your taxable income as if you did.

The building went up in value (hopefully), but your tax bill went down. That is the magic of depreciation. It is the most fundamental real estate tax benefit, and every investor should be using it. But it is just the starting point.

Pillar 2: Cost Segregation Studies

Cost segregation is where things start to get really interesting. Instead of depreciating your entire building over 39 years, a cost segregation study breaks the property down into its component parts. The HVAC system, the parking lot, the landscaping, the lighting, the plumbing, all of these things have shorter useful lives than the building itself.

An engineer comes in, literally walks through the property, and reclassifies those components into 5-year, 7-year, and 15-year depreciation buckets. And here is the kicker: with bonus depreciation, you can often deduct a massive chunk of those reclassified assets in year one.

Cost Segregation: Before vs. After

Without Cost Seg
$20,500
Annual depreciation
(39-year straight line)
With Cost Seg
$200,000+
Year-one deduction
(with bonus depreciation)

So instead of writing off $20,500 a year for 39 years, you might write off $200,000 or more in year one alone. That is a paper loss that gets applied against your real income. And this is why some investors specifically seek out properties with a lot of equipment, like car washes. You might look at a car wash selling at a 5.5% cap rate and think it does not make sense. But when you factor in the massive first-year depreciation from all that equipment, the after-tax returns look completely different.

A cost segregation study typically costs between $5,000 and $15,000, but the tax savings can be 10 to 20 times that amount. It is one of the highest-ROI investments you can make as a commercial real estate investor.

Pillar 3: 1031 Exchanges

A 1031 exchange lets you sell a property and defer all of the capital gains taxes by rolling the proceeds into a new like-kind property. And I mean all of them. Your tax bill on each sale is zero because you are deferring those gains. They roll forward and keep working for you in the next deal.

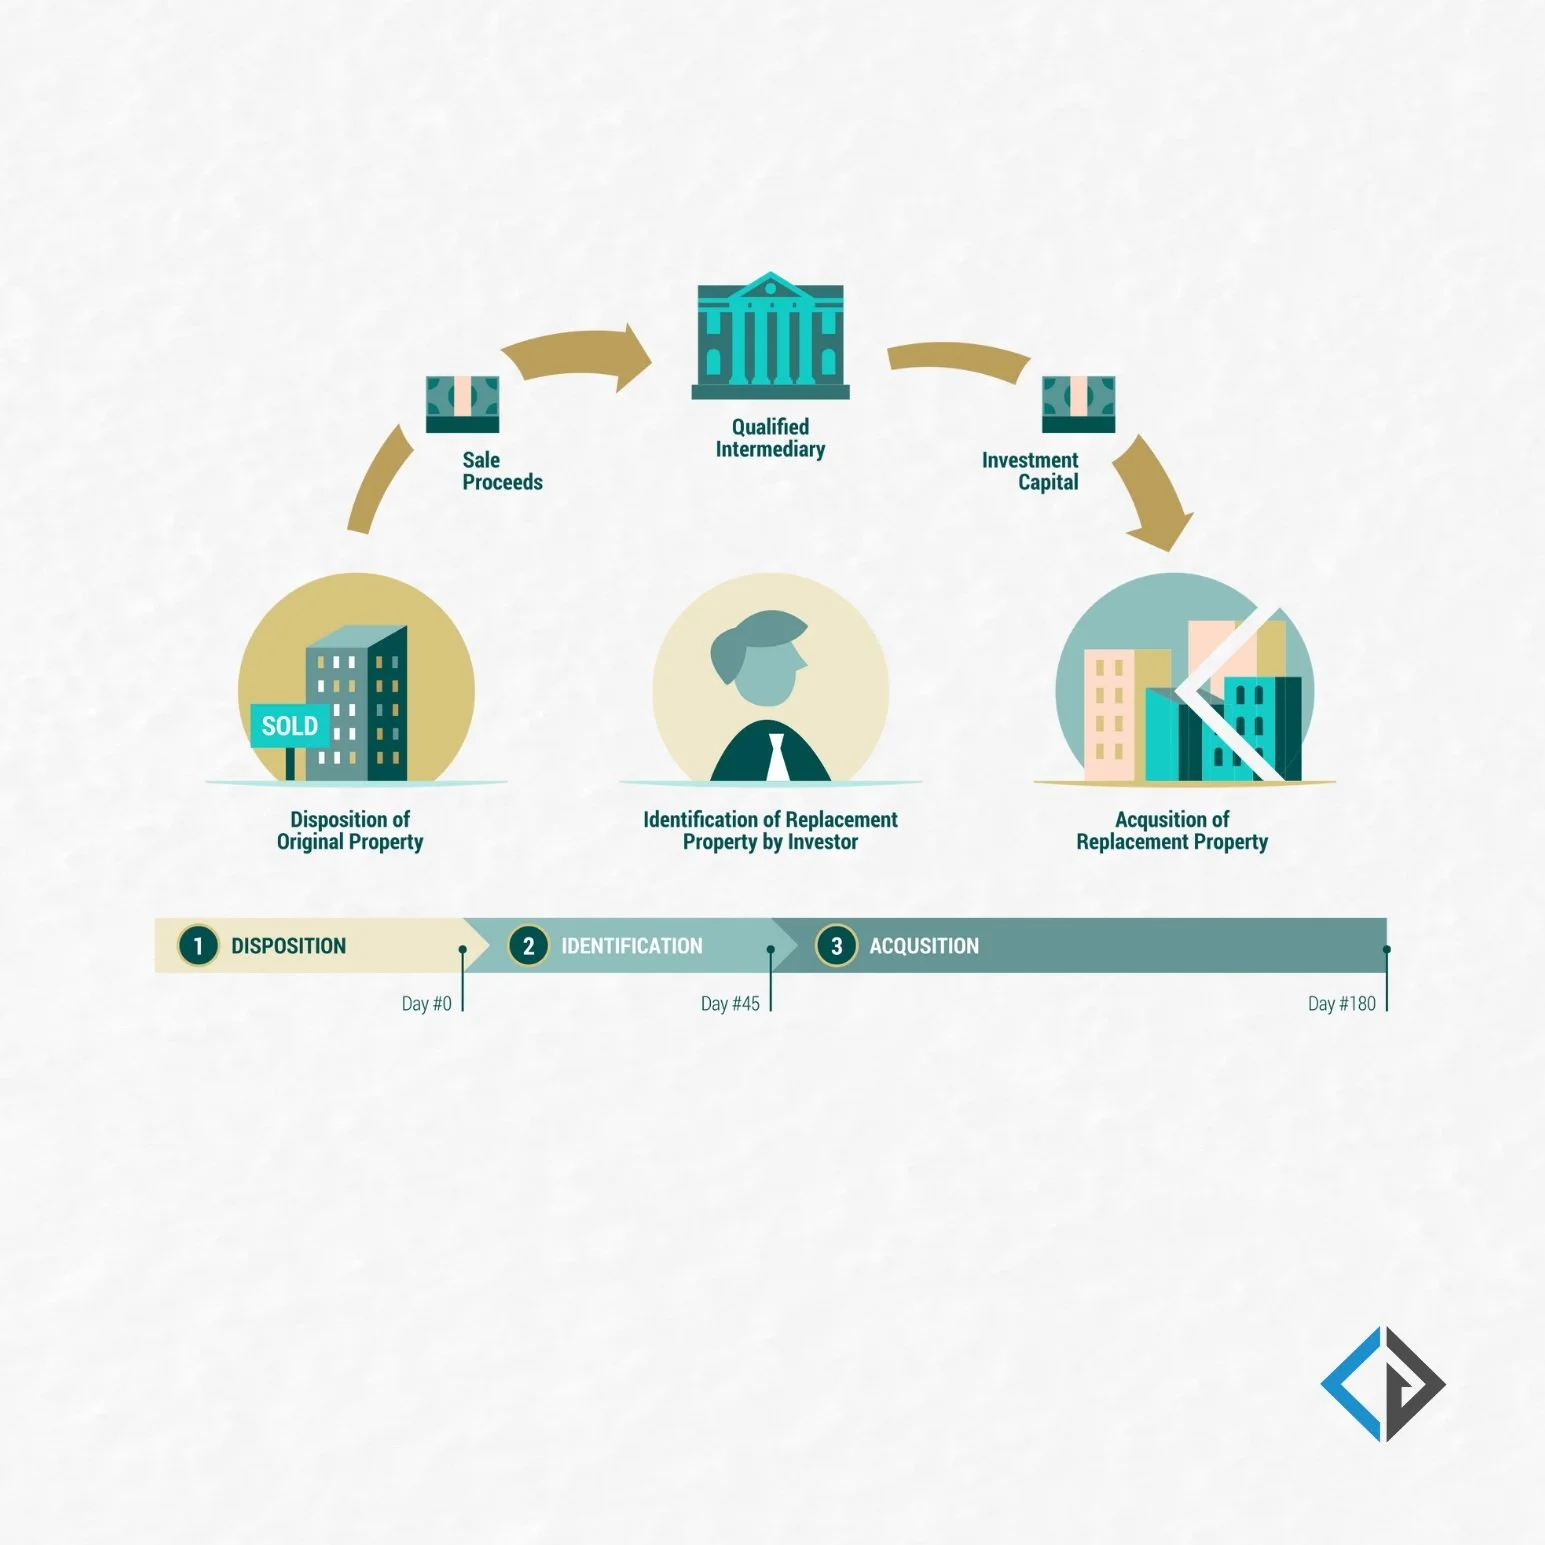
Here is how the timeline works. From the day of sale, you have 45 days to identify a replacement property. It could be two or three properties, or more depending on how you structure the exchange. Then you have 180 days from the sale to close on that replacement. If you do everything by the book and have a qualified intermediary guiding you through the process, you pay zero at the time of sale.

And here is what makes 1031 exchanges so powerful when combined with cost segregation: you buy a property, do a cost seg study, take massive depreciation in year one, hold the property for a few years, sell it via a 1031 exchange, and roll into a bigger property. Then you do it all over again. Each time you trade up, you are deferring gains and resetting your depreciation clock on a larger asset. The snowball keeps getting bigger.

"Buy, depreciate, 1031 exchange, repeat. Each time you trade up, you defer gains and reset your depreciation clock on a larger asset. The snowball keeps getting bigger."

Pillar 4: Borrow Against Equity, Don't Sell

This is the strategy that separates the good investors from the great ones. Instead of selling a property when you need to access your equity, you borrow against it. When you take out a loan, that is not a taxable event. You are pulling cash out of your property tax-free.

So let us say your building has appreciated from $1 million to $1.5 million. You refinance and pull out $300,000 in cash. That money is not income. It is debt. So you pay zero taxes on it. Meanwhile, the property continues to generate rental income and depreciation. You use the $300,000 as a down payment on your next property, and the cycle continues.

This is what wealthy real estate investors have been doing for decades. Buy, improve, hold, borrow against the equity, and acquire more. You never sell, so you never trigger capital gains. And the interest on the loan? That is deductible too.

A Real-World Example: $1M+ Income, $0 in Taxes

So how does all of this work in practice? Let me walk you through how my partner pulled it off last year. He stacked all four pillars together, and the results speak for themselves.

How He Netted $1M+ and Paid $0 in Taxes

Step 1: Depreciation

Baseline depreciation ran quietly in the background, offsetting rental income year over year.

Step 2: Cost Segregation

Frontloaded over $200,000 in paper losses into year one, applied against his real active income.

Step 3: 1031 Exchange

Sold properties and rolled gains into larger assets, deferring all capital gains taxes. Zero paid at each sale.

Step 4: Borrow Against Equity

Refinanced appreciated properties to pull out cash tax-free, then reinvested into more real estate.

By stacking all four strategies, he created enough paper losses to offset his entire active income. The IRS lets you do this. It is not a gray area. It is exactly how the tax code was designed to work for commercial real estate investors.

Key Takeaways: Real Estate Tax Benefits You Should Be Using

The tax code rewards real estate investors by design. The 1986 Tax Reform Act created structural advantages for investors who build, improve, and maintain real estate. These are not loopholes. They are incentives.

Depreciation is just the starting point. Straight-line depreciation is the baseline, but cost segregation can multiply your first-year deductions by 10x or more.

1031 exchanges let you defer taxes indefinitely. Sell one property, roll into the next, and pay zero capital gains at each step. Combined with cost seg, this creates a powerful compounding cycle.

Borrow against equity instead of selling. Refinancing pulls cash out tax-free while your property continues to generate income and depreciation.

You need a CPA who understands real estate strategy. Not just real estate. Strategy. A proactive CPA who helps you plan ahead is a completely different job than one who just files your returns.

This article is adapted from a live episode of The Commercial Real Estate Investor Podcast. If you want to go deeper on any of these strategies, check out the full video on the Tyler Cauble YouTube channel.

Want to learn how to start stacking these tax benefits in your own portfolio?

Learn About the CRE Accelerator
How to Buy a Hotel: From Airbnb Investor to $20M Hospitality Portfolio

I sat down with Michael Russell, co-founder of Malama Capital, on the podcast recently, and his story is one that I think a lot of real estate investors need to hear. Michael built a portfolio of 15+ Airbnbs in Maui, hit a wall, pivoted into commercial hospitality, bought a hostel during COVID at literally zero percent occupancy, and turned it into the number one rated hostel in North America. Today he's sitting on a $20 million portfolio that he built without a single dollar of outside capital.

If you've ever thought about how to buy a hotel or wondered whether there's a smarter path than traditional hotel investment, this is the conversation that'll change how you think about hospitality real estate.

Michael Russell: By the Numbers

$20M

Portfolio Value

#1

Rated Hostel in N. America

15+

Former Airbnb Units

$0

Outside Capital Used

Why Airbnb Investing Has a Ceiling

Michael got into short-term rentals the way a lot of people do. He was living in Maui, saw an opportunity, and started building out Airbnb units. At one point he had 15 to 17 properties running, and they were doing well from a cash flow standpoint. But here's the problem he ran into that most Airbnb investors eventually face: the model doesn't scale.

With Airbnbs, every guest wants a bigger, better experience. They want nicer furniture, better amenities, a more "exclusive" feel. And every improvement you make costs more money, but you can only charge so much per night for a single unit. You're also stuck with comp-based valuations. Your property is worth what the house next door sold for, regardless of how much revenue you're generating.

That's a fundamentally different game than commercial real estate, where your property value is driven by net operating income. If you can increase revenue or cut costs, you directly increase what the property is worth. Michael realized this when he took a course on buying apartment buildings, and it clicked for him. He thought, "What if I took the revenue potential of short-term rentals and combined it with the value-add mechanics of commercial real estate?" That's essentially the hospitality investing model.

How to Buy a Hotel: The Hostel Advantage

So here's where it gets really interesting from an investment standpoint. When Michael was looking at the hostel vs hotel comparison, the math was overwhelming.

Same 400 Square Feet, Two Very Different Outcomes

$200

per night as a hotel room

$480

per night as a hostel (8 beds x $60)

2.4x more revenue per square foot

Revenue per square foot is the metric that matters in hospitality investing. Not RevPAR, not ADR in isolation. It's about how much income you can generate from every square foot of space you're paying a mortgage on. And that's where the hostel model absolutely crushes traditional hotels.

Now, I know what you're thinking. "A hostel? Isn't that just a cheap, dingy backpacker spot?" That's exactly what I thought too before I started looking at modern hospitality concepts. But what Michael built in Maui is nothing like the hostels you're picturing. Think more along the lines of a boutique social hotel. Beautiful common areas, curated experiences, community focused. The kind of place where people actually want to hang out, not just crash for the night.

Buying a Hotel During COVID at Zero Occupancy

Michael's first hostel acquisition is a masterclass in buying when everyone else is running scared. He found a property in Maui that had been a hostel for 25 years under a single owner who had basically let the place fall apart. Deferred maintenance everywhere. And then COVID hit.

The property was at literally zero percent occupancy when Michael bought it. Nobody was traveling to Hawaii. The previous owner wanted out. And Michael saw what most people couldn't see through the panic: a fundamentally sound real estate asset in one of the most desirable travel destinations in the world, available at a steep discount because of temporary circumstances.

The best time to buy hospitality real estate is when nobody wants it. COVID created once-in-a-generation buying opportunities for investors who had the vision and the stomach to move forward.

- Tyler Cauble

He completely renovated the property, repositioned it as a boutique social hostel, and within a relatively short period of time, it became the number one rated hostel in North America. That's not luck. That's understanding how to add value to a commercial property through operational improvements and strategic repositioning.

The Financial Case: Hostel vs Hotel vs Short-Term Rental

Let's talk numbers, because this is where the hostel model really shines compared to both traditional hotels and Airbnb-style short-term rentals.

With a traditional Airbnb, you're capped. You can optimize your listing, improve your amenities, and maybe charge a premium, but at the end of the day you're renting one unit to one guest (or group). Your revenue ceiling is fixed by the nightly rate for a single booking.

With a hotel, you get more rooms, but each room takes up significant square footage and you're still limited to one booking per room per night. The overhead is massive: front desk staff, housekeeping for every room, higher furniture costs per unit.

The hostel model flips all of that. You're putting 6 to 8 beds in the same square footage that would hold one hotel room, and you're charging $50 to $80 per bed per night. The revenue density is dramatically higher. You need less housekeeping per guest, your common areas do double duty as amenities, and your per-guest acquisition cost is lower because hostels attract travelers who book based on community and experience, not just location.

And here's the kicker: because hospitality properties are valued on income (just like commercial real estate), every dollar of NOI you add directly increases your property value. There's much more room for error, and a much stronger value-add play.

Hospitality Is a Business and a Real Estate Investment

Here's the thing that Michael said that really stuck with me, and it's something I've experienced firsthand with Salt Ranch Hotel here in Nashville. Hospitality investing isn't just a real estate play. It's a real estate investment and a business investment wrapped into one.

When you buy an apartment building or an office complex, you're mostly managing a real estate asset. Collect rent, maintain the building, manage the tenants. Hospitality is a completely different animal. You're running a business every single day. You're managing staff, curating guest experiences, handling reviews, marketing to travelers, adjusting pricing in real time. It never stops.

Find a partner or mentor who has done it before. I would have given them an equity stake to help provide experience from the renovation to operational efficiency.

- Michael Russell, Malama Capital

That's Michael's biggest piece of advice for anyone looking at how to buy a hotel or hostel. Don't try to figure it all out yourself. The operational side of hospitality is complex, and having someone who's been through it before can save you hundreds of thousands of dollars in mistakes. I've lived this reality myself. Running a hotel is essentially two businesses at once.

What to Look for When Buying a Hotel or Hostel

Based on Michael's experience and what I've learned through my own commercial real estate career, here's what matters most when evaluating a hospitality acquisition. If you're still working through how to buy your first commercial property, this same checklist applies regardless of asset class:

Location fundamentals: Is the market driven by tourism, business travel, or both? Maui works because of consistent tourism demand year-round.

Revenue per square foot potential: Don't just look at room count. Calculate how much revenue each square foot can generate under different operating models.

Value-add opportunity: Deferred maintenance and outdated operations are your friends. They create the discount you need to make the numbers work.

Operational complexity: Be honest about whether you have (or can hire) the operational expertise to run a hospitality business.

Exit strategy: Hospitality properties are valued on income. Every operational improvement you make directly increases the value of the asset.

Key Takeaways

Airbnbs have a scaling ceiling. The model relies on comp-based valuations and doesn't reward operational improvements the way commercial real estate does.

The hostel model generates 2x+ revenue per square foot compared to traditional hotel rooms. 400 sq ft with 8 beds at $60/bed = $480/night vs $200/night as a single hotel room.

Buying distressed hospitality assets during downturns is where the biggest returns come from. Michael bought at zero occupancy during COVID and built the #1 rated hostel in North America.

Hospitality is a business AND a real estate investment. You need operational expertise, not just capital. Find a mentor or partner with experience before jumping in.

Revenue per square foot is the metric that matters. Focus on income density, not room count, when evaluating hospitality investments.


This article is adapted from a conversation on the Tyler Cauble YouTube channel. If you want to hear Michael's full story, including the details of his renovation process, his thoughts on scaling a hospitality portfolio, and how he built a $20 million business with zero outside capital, watch the full episode above.

Ready to Build Your Commercial Real Estate Portfolio?

Learn the strategies that top CRE investors and brokers use to find, analyze, and close deals.

Learn About the CRE Accelerator

90% of Her Warehouse Deals Come from Social Media, Not Cold Calling

I recently sat down with Aviva Sonenreich, managing broker at Warehouse Hotline in Denver and host of the Commercial Real Estate Secrets podcast. She's built an audience of over a million followers talking about commercial real estate on social media. And before you think that's some fluffy vanity metric, 90 to 95% of her actual brokerage deals come directly from her social media presence.

What Is a 1031 Exchange? Complete Guide to Real Estate 1031 Exchanges (2026)

What Is a 1031 Exchange? Complete Guide to Real Estate 1031 Exchanges (2026)

The 1031 exchange is one of the most powerful tools an investor can have in their arsenal for building wealth in real estate. It can help you improve your passive income, simplify property and asset management, assist with your estate planning, diversify your portfolio, and so much more. So, let’s dive on in to “What Is A 1031 Exchange?” in the real estate world.

How to Buy a Warehouse with $0 Down: A Step-by-Step Seller Financing Deal Breakdown

When Matt Barbaccia joined the CRE Accelerator back in November, the first thing he told me was, "Tyler, I feel underqualified for bigger deals." I hear that all the time. He had experience in residential real estate, he understood the fundamentals, but commercial felt like a different world. Fast forward 45 days, and Matt closed on his first commercial deal: a 70% vacant flex warehouse that he bought with zero dollars out of pocket using 100% seller financing. He set the record as a CRE Accelerator member for the fastest commercial deal ever closed.

33 Rental Houses vs. 1 Commercial Property: Why the Math Favors Commercial

I get asked all the time: "Tyler, how many rental houses do I need to replace my income?" And the answer is one of the biggest reasons I shifted my entire investment strategy toward commercial real estate. Because when you actually sit down and run the numbers on residential rental properties versus a single commercial property investment, the math is going to shock you.

He Sold His Apartments, Bought a Commercial Building, and Made $100k

Chad Acerboni isn't a full-time real estate investor. He's a tech sales executive who's been quietly building a portfolio on the side, one intentional move at a time. And his latest move? Selling his apartment complex, paying zero taxes on the sale via a 1031 exchange, and closing on a 30,000 square foot mixed-use commercial building for $2.1 million. The appraisal already came back higher than his purchase price.

Gold vs Real Estate: Why Commercial Property Beats Gold Every Time

Every time gold spikes, I hear the same thing: "Tyler, should I be buying gold right now?" And I get it. Gold just hit record highs, people are nervous about the economy, and there's something psychologically comforting about owning a shiny metal that's been valuable for 5,000 years. But here's what I always tell people: gold doesn't pay you. It just sits there. Commercial real estate? It pays you every single month while simultaneously growing in value.

Why Ghost Kitchens Failed: The $1 Billion Real Estate Lesson Nobody Saw Coming

In September 2019, RXR Realty, which had $18.8 billion in assets, made what looked like one of the smartest bets in commercial real estate at the time: a $40 million investment in Kitchen United, a ghost kitchen operator filling vacant retail space with delivery-only restaurants. Four years later, Kitchen United closed every single location and sold off all of its assets.

Commercial Real Estate Underwriting: Complete Guide (2026 + Real Deal Walkthrough)

Commercial Real Estate Underwriting: Complete Guide (2026 + Real Deal Walkthrough)

Today, I'm going to walk you through commercial real estate underwriting, and more importantly, I'm going to show you why it matters. Not just how to plug numbers into a spreadsheet, but why each piece of the puzzle actually affects your decision to buy or pass on a deal.

How to Start a Boutique Hotel: Lessons from Building Salt Ranch

I built the Salt Ranch hotel brand from the ground up. It wasn't my first real estate deal, but it was my first hotel. And if you're thinking about starting a boutique hotel, I want to walk you through exactly what that looks like, from day one to opening day.

How to Build a Hotel: The Development Timeline Nobody Talks About

Here's what nobody tells you about building a hotel: the spreadsheet and the reality look nothing alike. I've learned this the hard way with Salt Ranch. And I'm going to walk you through exactly what happened, because if you're thinking about hotel development or commercial real estate development, you need to know this stuff.

Boutique Hotel Design: How We Turned a 1950s Motel into Salt Ranch Nashville

When I first walked onto that 2.5 acres in East Nashville, I saw a tired 1950s motel. The bones were there, sure. But the design was dated, cramped, and honestly, forgettable. I knew right then that boutique hotel design would make or break this project. And I wasn't interested in another cookie-cutter renovation. I wanted something that felt like Palm Springs met Southern hospitality. Something locals would actually want to hang out at, not just tourists passing through.

How I Analyzed a $3 Million Motel Deal: Real Estate Deal Analysis for Salt Ranch

Finding the right property for Salt Ranch wasn't about luck. It was about knowing exactly what I wanted and having the discipline to wait for it. When the Congress Inn property on Dickerson Pike came up, I knew within the first few hours that this was it. But before I could commit $3 million to the deal, I needed to know everything: the market, the zoning, the feasibility, the competitive landscape. That's what this post is about. I'm walking you through my entire due diligence process so you can apply the same framework to your next deal.

How to Finance a Boutique Hotel: What 50 Lender Rejections Taught Me About Hotel Financing

When I tell people that over 50 lenders said no to financing Salt Ranch, they usually think I'm exaggerating. I'm not. Hotel financing is one of the most difficult parts of any hotel development project, and if you're trying to do it without a flag (meaning no Hilton, Marriott, or other brand name attached), it gets exponentially harder.

How an Old Roadside Motel Became Salt Ranch: The Full Story of Building a Boutique Hotel in Nashville

Most people will never build their own hotel. It's not exactly something you wake up one day and decide to do. But somehow, I ended up buying an old roadside motel on Dickerson Pike in East Nashville and spending the better part of four years turning it into a boutique hotel in Nashville unlike anything else in the city.

How to Value Commercial Property When It's Completely Vacant

Most people look at a vacant commercial building and freeze. No tenants, no income, no idea what it's worth. So they either lowball and lose the deal, or they overpay because some broker convinced them to pay tomorrow's value at today's price.

I've been there. And I can tell you, vacancy doesn't mean a building is worthless. It just means you have to be smarter about how you price it.

This came up on our CRE Accelerator mastermind call recently. One of our members, Ryan, was working on a deal where there were only four or five comparable sales in the last year. Not a lot to go on. So I walked the group through exactly how I back into a maximum allowable offer on a vacant commercial property. And I'm going to walk you through it right now.

Here's what we'll cover:

  • Estimating realistic market rent per square foot

  • Converting rent into NOI (net operating income)

  • Applying a cap rate to find stabilized value

  • Building in your required returns and risk margin

  • Two methods for calculating your maximum allowable offer

  • Budgeting for TI, lease-up commissions, and carry costs

Let's get into it.

Start With Market Rent Per Square Foot

When a property is vacant, you don't have a rent roll to work with. So you have to estimate what the building can rent for once it's stabilized.

Here's how I do it. I look at comparable properties in the area. Similar size, similar condition, similar use. I check what's listed for rent on LoopNet and Crexi. And then I call brokers. That second part is key. Asking rents and signed rents are two very different things. Most brokers, if you've built a good relationship with them, will tell you what deals are actually getting done in your market.

I also pull data from every offering memorandum I can get my hands on. Every time a property hits the market for sale in East Nashville, I grab the OM. It shows the rent rolls, the lease terms, the asking cap rate, all of it. I catalog everything because that data compounds over time. The more you have, the more accurately you can underwrite your next deal.

So let's say you've done your homework and you've determined that market rent for your building is $18 per square foot on a triple net basis.

Calculate the Net Operating Income

Now we turn that rent number into an NOI. This is where a lot of newer investors trip up, so let me break it down.

If you're not familiar with how to underwrite your first commercial deal, the basic formula is simple: your effective gross income minus your operating expenses equals your NOI.

Let's use a clean example. Say we've got a 10,000 square foot building at $18 per square foot triple net. That gives us:

$18 x 10,000 SF = $180,000 per year in gross income

Now, even on a single-tenant deal with a 10-year lease, a bank is going to apply a vacancy factor. Typically around 5%. So:

$180,000 x 5% vacancy = $9,000

That drops your effective gross income to $171,000.

From there, you need to account for operating expenses. A good rule of thumb: your operating expense ratio should land somewhere around 35% of gross income. If you're down near 20%, you're probably not maintaining the property well enough, and that'll catch up with you in deferred maintenance. If you're pushing 50%, something's off.

At 35%, your operating expenses come out to roughly $59,850, which gives you an NOI of about $111,150.

Now, the lease structure matters here. On a triple net deal, your tenants are reimbursing you for CAM, taxes, and insurance, so your P&L will show gross rent minus those expenses to arrive at base rent. On a full-service gross lease, you're eating all of those costs yourself, and the math gets more involved. For this example, we'll keep it at our $111,150 NOI.

Apply a Cap Rate to Find Stabilized Value

Here's where you determine what the property could be worth once it's leased up and producing income.

The formula is one you've probably seen before: Value = NOI / Cap Rate.

But the real question is, what cap rate do you use? And this is where all of those offering memorandums I mentioned earlier become gold. You need to understand what properties in your market are trading for. Not nationally. Not some number you pulled off the internet. Your market, your asset class, your condition level.

If you've been tracking deals in your area (and you should be), you might determine that a building like this, with these types of tenants, in this condition, would trade at roughly a 7% cap rate.

So: $111,150 / 0.07 = approximately $1,590,000

That's your stabilized value. That's what the building could be worth after you've done the work. Leased it up, stabilized the income, and gotten everything running.

But that is absolutely not what you should pay for it today.

I've seen this trap more times than I can count. A broker will say, "Hey, once you come in and lease this up, it'll be worth $1.59 million at a 7 cap. So that's the price." I know it sounds ridiculous, because it is, but brokers will try to sell you the future value today. Don't fall for it.

Two Methods to Calculate Your Maximum Allowable Offer

Now that you know the stabilized value, you need to figure out the most you can actually pay and still make the deal work. There are two ways I approach this.

Method 1: The 75-80% Rule

This one is simple. You take the stabilized value and multiply it by 75% (or 80%, depending on your risk tolerance). That builds in a margin for your profit, your risk, and all the costs associated with getting the building to stabilization.

$1,590,000 x 75% = $1,192,500 all-in maximum

That means your purchase price plus closing costs, tenant improvements, lease-up commissions, carry costs, everything, can't exceed $1,192,500.

This method is fast and gives you a solid ceiling. But it can miss some of the finer details.

Method 2: Subtract Your Required Returns

This is how I prefer to do it because it forces you to think through every dollar.

I always aim for a 2x equity multiple over five years. That means if I put $100,000 into a deal, I need $200,000 back in five years, including cash flow, sale proceeds, everything.

Let's say I'm planning to bring $300,000 down on this deal. At a 2x multiple, I need $600,000 back.

So I take the stabilized value and subtract my required profit:

$1,590,000 - $600,000 = $990,000 maximum purchase price

But we're not done. What about capital improvements? Let's say TI and renovations will cost $150,000. Now:

$1,590,000 - $600,000 - $150,000 = $840,000 maximum purchase price

At $840,000, I'm basically doubling the value of the property to make the returns work. That tells me this deal requires real value creation, and I need to be confident I can execute.

Don't Forget the Hidden Costs

Here's where a lot of investors get burned. They budget for the down payment and forget about everything else.

When I'm stress-testing a deal, I make sure I'm accounting for:

Closing costs. Typically 1-2% of the purchase price.

Leasing commissions. On our 10,000 SF example at $18/SF on a 5-year lease, that's a $900,000 total lease value. At 6% commission, you're looking at $54,000 in leasing costs.

Tenant improvements. This varies wildly. For second-generation space in decent shape, you might be able to match your rent rate ($12-16/SF in TI for $12-16/SF in rent). For a dark shell where you're building out bathrooms and HVAC from scratch, you could be looking at $24-32/SF. On 10,000 SF, that's anywhere from $120,000 to $320,000.

Carry costs. If the building sits vacant for six months while you're leasing it up, you're paying the mortgage, the utilities, the insurance. That adds up fast.

Construction contingency. Because you never know what's behind the walls. I recently tore open a wall on a deal and found electrical from the 1940s with no sleeves. Fire hazard. Cost me $180,000 to fix. That's why you always carry contingency in your construction budget.

A Smart Move on Tenant Improvements

Here's something I want you to keep in your back pocket. You can actually structure TI as a win-win by amortizing the cost into the lease.

Say a tenant wants $10/SF in improvements on a 5,000 SF space. That's $50,000. If you amortize that at 8% over the 60-month lease term, it adds roughly $1,000/month to their rent. Over 60 months, you collect about $60,000 on a $50,000 investment. That's a 20% return just on the TI dollars alone.

That's why sometimes it's actually better for you to do the improvements than not. It just depends on how you structure the lease.

Key Takeaways

Vacant doesn't mean valueless. You just have to underwrite future income and back into what you can pay today.

Start with market rent. Use comps, OM data, LoopNet, Crexi, and broker conversations to nail down realistic rent per square foot.

NOI and cap rate give you stabilized value. Value = NOI / Cap Rate. Track offering memorandums in your market so you know what realistic cap rates look like for different asset types.

Build in real margins. I target a 2x equity multiple over 5 years. Your MAO needs to leave room for both value creation and investor returns.

Use both MAO methods. The 75-80% rule is quick and clean. The subtract-your-returns method is more precise. I'd recommend running both and seeing where they land.

Budget beyond the down payment. Closing costs, TI, leasing commissions, construction, carry costs. These can push your all-in basis way higher than you planned.

Never pay tomorrow's value today. If a broker is pricing a vacant building at stabilized value, walk away.

This article is adapted from Office Hours on the Tyler Cauble YouTube channel.

Want to learn how to underwrite deals like this with confidence? Check out the CRE Accelerator, my step-by-step program for building your commercial real estate portfolio. We cover underwriting, deal analysis, and everything else you need to start investing in commercial real estate.

Why Most Real Estate Developers Go Broke Before Breaking Ground

Real estate development looks glamorous from the outside - big projects, big returns, and the thrill of building something from nothing. But the reality is far more brutal. Most developers go broke before they ever break ground, and the ones who survive often do so by learning lessons that nearly destroyed them first.

From Chaos to Clarity: Lessons From a Decade in Development

From Chaos to Clarity: Lessons From a Decade in Development

Meg Epstein didn’t set out to become a developer.

She started on the construction side—project managing ultra-high-end residential builds in California, the kind of homes where details matter, timelines stretch for years, and execution is everything. That job-site foundation gave her an operator’s mindset early: budgets are real, plans have consequences, and the smallest misstep can snowball fast.

When she moved to Nashville in 2016, she immediately saw opportunity where most people saw “no thanks”—especially along the river. While locals dismissed it as industrial and undesirable, Meg saw a future neighborhood: proximity to downtown, walkability, and an overlooked waterfront that felt obvious coming from markets like San Francisco.

But her real credibility wasn’t built in the easy wins—it was forged in the early deals where she had to figure things out in real time.

On her first major project, she entered as the financial partner to a developer, raised capital through cold outreach (not a built-in friends-and-family network), and quickly learned that the plan on paper doesn’t matter if the deal doesn’t pencil. When the original approach fell apart, she had to step into the developer seat midstream—scrapping work, restructuring the plan, and making high-stakes decisions under pressure.

That pattern—being forced into clarity when everything gets messy—became the theme of her next decade. She went on to build through multiple cycles, experience the “frothy” highs of 2022, and then endure the whiplash of rising rates, dried-up equity, and tough operational resets. And on the other side of that volatility, she rebuilt her business model with tighter focus, a leaner team, and a clearer definition of what she actually wants the business to support.